Note: This article is written in standard American English and synthesizes current U.S. budgeting guidance, federal spending data, housing affordability standards, cost-of-living research, transportation cost data, rental market insights, and consumer finance best practices. No source links are embedded in the copy for cleaner web publishing.
The 50/30/20 rule sounds beautifully simple: spend 50% of your take-home pay on needs, 30% on wants, and 20% on savings or debt repayment. It is the budgeting equivalent of a three-ingredient recipe. Unfortunately, life occasionally behaves less like a recipe and more like a toddler with a glitter cannon. Where you live can make this rule easy, difficult, or downright hilarious in a “my rent costs what?” kind of way.
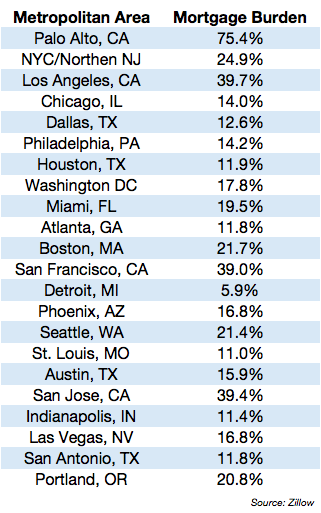
A person earning $5,000 a month after taxes in Kansas City, Missouri, may have a completely different financial reality than someone earning the same amount in San Francisco, New York City, Boston, Honolulu, Seattle, or Los Angeles. The paycheck may look identical on paper, but rent, transportation, groceries, insurance, taxes, childcare, and utilities can stretch or squeeze that money in very different ways.
That does not mean the 50/30/20 rule is useless. In fact, it can be extremely helpful. But it works best when treated as a flexible financial framework, not a strict law delivered from the summit of Mount Spreadsheet. The key is understanding how location changes your budget, then adjusting the rule without abandoning the goal: covering essentials, enjoying life responsibly, and building a stronger financial future.
What Is the 50/30/20 Rule?
The 50/30/20 budget rule divides your after-tax income into three broad categories:
50% for Needs
Needs are the expenses required to keep your life running. These include rent or mortgage payments, utilities, groceries, transportation, health insurance, minimum debt payments, basic clothing, childcare, and essential phone or internet service. In other words, needs are the bills that keep you housed, fed, mobile, insured, and reasonably functional as an adult.
30% for Wants
Wants are the things that make life enjoyable but are not absolutely required. Dining out, streaming subscriptions, vacations, upgraded tech, concerts, gym memberships, hobbies, and that suspiciously expensive latte with oat milk and emotional support foam all live here. Wants are not bad. A budget that allows no joy is usually a budget waiting to be abandoned.
20% for Savings and Debt Repayment
This category includes emergency savings, retirement contributions, extra debt payments, investments, sinking funds, and other long-term financial goals. It is the category that helps your future self avoid sending your present self a strongly worded complaint letter.
The beauty of the 50/30/20 rule is that it is easy to understand. Instead of tracking 47 tiny categories, you focus on three big buckets. But the challenge appears when your “needs” category is already devouring half your income before you have bought groceries or replaced the tire that mysteriously found a nail on Tuesday.
Why Where You Live Changes Everything
Location is one of the biggest forces shaping a household budget. The same salary can feel comfortable in one city and painfully tight in another. Regional price differences are real, and they show up most clearly in housing, transportation, taxes, insurance, and everyday services.
For many Americans, housing is the budget’s heavyweight champion. A common affordability guideline says housing costs should ideally stay around 30% of gross income or less. But many renters spend more than that, especially in high-cost metro areas. Once rent or mortgage payments climb above that line, the classic 50% “needs” category can become crowded quickly.
Transportation is another major location-based expense. In a walkable city with reliable public transit, someone may avoid owning a car altogether. In a suburb or rural area, a car may be non-negotiable. That means fuel, insurance, maintenance, registration, repairs, parking, and possibly a car payment. A cheaper rent payment outside the city can sometimes be offset by higher commuting costs. The apartment may be cheaper, but your gas tank may start acting like it has a taste for luxury.
Food costs also vary by region. Groceries, restaurant prices, local taxes, and access to discount stores can change how much a household spends. Childcare, healthcare, renters insurance, homeowners insurance, and utility bills can also differ sharply depending on climate, state regulations, local supply, and household size.
How the 50/30/20 Rule Looks in Different Places
Let’s say two people each bring home $5,000 per month after taxes. Under the standard 50/30/20 rule, the monthly budget would look like this:
- Needs: $2,500
- Wants: $1,500
- Savings and debt repayment: $1,000
Now place one person in a lower-cost city where rent is $1,200, utilities are $250, groceries are $500, and transportation is $350. Their needs may fit comfortably under $2,500. They can save $1,000, enjoy $1,500 in wants, and still have enough breathing room to avoid checking their bank app with one eye closed.
Now place the second person in a high-cost city where rent is $2,200, utilities are $250, groceries are $650, transit or car costs are $300, and insurance plus medical costs add another $250. Needs could easily reach $3,650. That is 73% of take-home pay, before wants and savings even enter the room. The 50/30/20 rule has not failed; the local cost structure has changed the math.
When Needs Take More Than 50%
If your needs exceed 50% of your take-home income, you are not automatically “bad with money.” You may simply live in an expensive area, have dependents, carry student loans, need a car for work, or face high healthcare or childcare costs. Personal finance advice often sounds tidy until real life walks in wearing muddy boots.
When essentials are too high, the first step is not shame. The first step is diagnosis. Break down your needs into housing, transportation, groceries, insurance, utilities, debt minimums, childcare, and healthcare. Then identify which expenses are fixed, which are flexible, and which are connected to where you live.
Housing and transportation should be viewed together. A cheaper apartment 30 miles away may not actually save money if it adds tolls, fuel, vehicle wear, parking, and two extra hours of commuting each day. On the other hand, paying slightly more to live near work or transit may lower transportation costs and improve quality of life. The cheapest choice on paper is not always the cheapest choice in real life.
How to Adjust the 50/30/20 Rule by Location
The goal is not to worship the percentages. The goal is to build a sustainable plan. Depending on where you live, you may need a modified version of the rule.
Option 1: The High-Cost City Version: 60/20/20
If housing and transportation are expensive, you might use 60% for needs, 20% for wants, and 20% for savings. This keeps the savings goal alive while trimming lifestyle spending. It is not as glamorous as the original split, but neither is paying $19 for a salad that appears to contain three leaves and a motivational quote.
Option 2: The Debt-Payoff Version: 50/20/30
If your needs fit within 50% but debt is a priority, you could shift to 50% needs, 20% wants, and 30% savings or debt repayment. This approach works well for people trying to eliminate credit card balances, build an emergency fund quickly, or catch up on retirement savings.
Option 3: The Starter Version: 70/20/10
For lower-income households, students, new workers, single parents, or people in very expensive areas, 70% needs, 20% wants, and 10% savings may be more realistic. Saving 10% consistently is better than promising yourself 20%, failing every month, and deciding budgeting is a scam invented by people who enjoy color-coded folders.
Key Location Factors to Review Before Choosing Where to Live
Before moving to a new city, renewing a lease, or buying a home, compare more than rent or mortgage payments. A smart location-based budget includes the full cost of living.
Housing Costs
Look at rent, mortgage payments, property taxes, homeowners insurance, renters insurance, HOA fees, maintenance, and utilities. Rent may be predictable, while homeownership can include surprise expenses such as roof repairs, plumbing issues, appliance replacement, and the mysterious ability of houses to create $800 problems overnight.
Transportation
Consider whether you need a car. If yes, include payments, insurance, fuel, repairs, tires, parking, tolls, registration, and depreciation. If no, calculate transit passes, rideshares, bike maintenance, and occasional rentals. In some cities, living car-free can free up hundreds of dollars per month. In others, trying to live without a car may turn every errand into a mini survival documentary.
Taxes
State income taxes, sales taxes, property taxes, and local taxes can shift your real take-home pay. A state with no income tax may still have higher property taxes, insurance costs, or sales taxes. Always compare the full tax picture, not just the headline.
Income Opportunities
A high-cost city may also offer higher wages, stronger job networks, better career growth, and more side-income opportunities. A low-cost area may reduce expenses but also limit earnings in certain industries. The best budget is not always found in the cheapest location; it is found where income and expenses create the strongest gap in your favor.
Insurance and Climate
Homeowners insurance, renters insurance, auto insurance, and utility bills can be affected by weather, natural disaster risk, traffic patterns, crime rates, and state rules. Hot climates may mean higher cooling costs. Cold climates may mean higher heating bills. Coastal areas may bring higher insurance premiums. Your zip code can quietly influence your budget like a ninja accountant.
Practical Examples of Location-Based Budgeting
Imagine a single professional earning $4,500 per month after taxes in a mid-sized city. Rent is $1,250, utilities are $220, groceries are $450, transportation is $400, insurance and healthcare cost $250, and minimum debt payments are $200. Total needs are $2,770, or about 62% of take-home pay. A strict 50/30/20 plan will feel unrealistic. A better plan may be 62% needs, 18% wants, and 20% savings, at least temporarily.
Now consider a couple earning $8,000 per month after taxes in a suburb. Their mortgage is $2,100, utilities are $350, groceries are $900, two cars cost $1,200 combined, insurance and healthcare cost $600, and childcare costs $1,400. Their needs total $6,550, or about 82% of take-home pay. The issue is not too many brunches. The issue is a major structural cost: childcare plus transportation plus housing. They may need bigger changes, such as adjusting work schedules, refinancing, changing insurance plans, carpooling, relocating closer to work, or increasing income.
Finally, imagine a remote worker earning $6,000 per month after taxes who moves from a high-rent city to a smaller metro. Rent drops from $2,400 to $1,400, but car costs rise from $100 in transit passes to $650 in total driving expenses. The move still saves $450 per month, but not the full $1,000 suggested by rent alone. This is why location decisions should include the whole budget, not just the rent listing that looks charming until you notice the nearest grocery store is a 27-minute drive away.
How to Make the 50/30/20 Rule Work Wherever You Live
Start with your actual take-home pay. Do not use gross salary unless you enjoy budgets that look fantastic and then collapse immediately. Include regular income only. Bonuses, tax refunds, and irregular freelance payments can support savings goals, but they should not be required to pay the electric bill.
Next, track one to three months of spending. Sort each expense into needs, wants, or savings and debt repayment. Be honest. Groceries are a need. Imported cheese shaped like a tiny vacation is probably a want. A basic phone plan may be a need. The deluxe plan with every streaming bundle known to civilization may need a small courtroom hearing.
Then calculate your real percentages. If your needs are 58%, wants are 27%, and savings are 15%, you now have a starting point. You can decide whether to cut wants, reduce fixed costs, increase income, or gradually improve savings. Progress matters more than perfection.
Automate what you can. Set up automatic transfers to savings after payday. Automate retirement contributions if available. Use separate accounts for bills, emergency savings, and flexible spending. The less your budget relies on daily willpower, the better. Willpower is wonderful, but it has been known to lose fights with pizza.
Smart Ways to Lower Location-Based Costs
Reducing expenses does not always mean moving across the country. Start with the biggest categories.
For housing, consider roommates, negotiating lease renewal terms, moving at a less competitive time of year, choosing a slightly smaller place, or living near transit to reduce car costs. Homeowners can review insurance, appeal property tax assessments where appropriate, improve energy efficiency, or rent out unused space if local rules allow.
For transportation, compare the real cost of owning a vehicle against transit, carpooling, biking, walking, or using one car instead of two. If you must drive, shop insurance annually, maintain your vehicle, combine errands, and avoid upgrading cars simply because your current one lacks a touchscreen large enough to host a movie night.
For food, use meal planning, store brands, loyalty programs, bulk buying when practical, and fewer convenience purchases. The goal is not to turn dinner into an accounting seminar. The goal is to keep food spending intentional.
For utilities, review energy usage, insulation, thermostat settings, phone plans, internet packages, and subscription creep. Many budgets do not collapse because of one giant purchase. They leak slowly through ten small monthly charges with names like “Premium Plus Unlimited Deluxe.”
When Moving Might Be the Best Financial Decision
Sometimes the numbers make a strong case for moving. If housing consistently consumes too much income, if job opportunities are better elsewhere, or if transportation costs are draining your budget, relocation may be worth considering. However, moving has costs too: deposits, movers, lease breaks, furniture, time off work, new insurance rates, and emotional energy. A cheaper city is not automatically better if it reduces your income, support network, or career growth.
Before moving, compare at least three scenarios: staying where you are, moving nearby, and relocating to a different city or region. Estimate take-home pay, housing, transportation, taxes, healthcare, childcare, insurance, and lifestyle costs. Also consider non-financial factors such as family support, safety, schools, commute time, and quality of life. A budget should support a life, not just win a math contest.
Personal Experiences and Real-Life Lessons: Where You Live Changes the 50/30/20 Rule
One of the most useful lessons from applying the 50/30/20 rule is that the budget rarely fails because someone bought one nice coffee. It usually struggles because the biggest life choices are expensive: where you live, how you commute, whether you need childcare, and how much fixed debt follows you around like a very boring pet.
Consider the experience of moving from a dense urban neighborhood to a cheaper suburb. At first, the lower rent feels like winning a small lottery. The apartment is bigger, the parking is easier, and nobody is charging extra for a closet that has been optimistically marketed as a “home office.” But after a few months, the transportation costs become clearer. Gas costs rise. Car insurance changes. Weekend errands take longer. The person who once walked to the grocery store now drives everywhere. The budget improves, but not as dramatically as expected.
Another common experience happens in high-cost cities. Someone may earn a strong salary and still feel behind. Friends in lower-cost areas may wonder how a higher income disappears so quickly. The answer is usually not reckless spending. It is rent, taxes, transit, insurance, and everyday services priced at big-city levels. In these situations, the 50/30/20 rule becomes a measuring tool rather than a commandment. It reveals that the person may need a 60/20/20 plan for a while, especially if staying in that city supports career growth.
Families often experience the rule differently than single adults. A single person can reduce costs by getting roommates, using public transit, or living in a smaller space. A family may need more bedrooms, safer schools, childcare, reliable transportation, and health coverage. Suddenly, “needs” are not just rent and groceries; they include an entire support system. For parents, a realistic budget may require temporarily lowering the wants category while protecting emergency savings as much as possible.
Remote workers have discovered another lesson: income and location can be separated, but not always perfectly. Moving to a lower-cost area while keeping a higher-paying job can make the 50/30/20 rule much easier. However, remote work may come with trade-offs. Internet quality matters. Home office costs increase. Some employers adjust pay based on location. Social life may change. The best move is one that improves both the spreadsheet and daily happiness.
The most practical experience is this: budgets should be reviewed after every major life change. A raise, move, marriage, baby, job change, car purchase, medical expense, or rent increase can shift the percentages. The 50/30/20 rule is not a one-time setup. It is more like a financial thermostat. When life gets hotter or colder, adjust it.
People who succeed with this rule tend to use it with honesty and flexibility. They do not pretend that a high-rent apartment costs less than it does. They do not label every want as a need just because the want is emotionally persuasive. They also do not give up when the percentages are imperfect. Instead, they ask better questions: Can I lower fixed costs? Can I earn more? Can I save 10% now and build toward 20%? Can I choose a neighborhood that gives me a better balance of rent, commute, safety, and opportunity?
In the end, where you live shapes the 50/30/20 rule, but it does not have to control your entire financial life. The rule gives you a map. Your location adds the terrain. The smartest budget uses both.
Conclusion
The 50/30/20 rule is a powerful budgeting framework because it keeps money management simple. But your zip code can change everything. Housing, transportation, taxes, food, insurance, childcare, and income opportunities all affect whether the classic split is realistic. Instead of forcing your life into perfect percentages, use the rule as a guide. If your needs are too high, adjust the formula, reduce major costs where possible, and protect savings even if you have to start smaller.
A good budget is not about looking perfect on paper. It is about helping you live with less stress, more clarity, and a better plan for the future. Whether you live in a pricey coastal city, a budget-friendly small town, a fast-growing suburb, or somewhere in between, the best version of the 50/30/20 rule is the one that reflects your real life and keeps you moving forward.