If you’ve ever tried to pay a real-life bill with a “strong long-term return profile,” you already know the problem:
your landlord does not accept charts. They want money. Preferably on the first of the month. Preferably in dollars.
That’s why the idea behind “Creating Monthly Income From Your Portfolio”featured in the
Talk Your Book series on Animal Spirits and posted on A Wealth of Common Sensehits a nerve in the best way.
It’s not just “How do I invest?” It’s “How do I turn investing into something that behaves like a paycheck?”
In that episode, the conversation orbits around a very modern income toolkit: options-based income strategies that aim to
deliver consistent monthly distributions while still keeping equity exposure. But the bigger takeaway isn’t “go buy this thing.”
The bigger takeaway is how to think clearly about incomewithout chasing shiny yields that look great on paper and feel terrible
in real life.
What “Talk Your Book” Is Really About (Beyond the Name)
Talk Your Book is basically a sponsored deep dive: the hosts bring on an investment professional and ask the questions
regular humans would ask if they weren’t trying to sound smart at a cocktail party. This particular episode focuses on
maintaining diversification while earning yield, how options strategies can create monthly income,
andmy favorite partwhat could go wrong.
That last one matters because “income” is one of those words that can lull investors into a false sense of safety.
People hear “monthly income” and think “stable.” Meanwhile, markets hear “monthly income” and say,
“Cute. Anyway, here’s volatility.”
Monthly Income vs. Portfolio Income (They’re Not the Same Thing)
Let’s clear up a classic confusion: income is cash flow you receive (dividends, interest, option premiums, distributions).
Total return is the full result (income plus price changes).
In accumulation years, many investors obsess over total return because the goal is growth. In retirementor anytime you’re living
on your portfolioyour goal shifts. You still want growth (inflation never retires), but you also want
dependable cash flow.
Here’s the catch: building a portfolio that throws off a high yield can quietly change the portfolio’s risk profile.
“More yield” often means “more concentration,” “more credit risk,” “more option risk,” “more fees,” or the old classic,
“more things you didn’t realize you signed up for.”
The paycheck illusion (and why it’s powerful)
A monthly distribution can be psychologically helpful. It can make investing feel like income rather than an abstract number
bouncing around on a screen. For many people, that structure prevents panic-selling because they’re focused on the cash flow.
But it can also backfire if you start believing a high distribution rate is the same thing as a guaranteed paycheck.
The Three Engines of Monthly Cash Flow
Most “monthly income from your portfolio” plans use one or more of these engines:
1) Dividends (the familiar friend)
Dividend stocks and dividend-focused funds can provide steady cash flow. They also come with trade-offs:
dividend payouts can be cut, dividend-heavy portfolios can become sector-skewed, and chasing the highest yield can lead you
straight into companies that are flashing warning signs like a cartoon anvil about to fall.
Dividends can be tax-efficient when they qualify for favorable rates, but tax treatment varies.
Some distributions are ordinary income, and some payments investors call “income” may actually be return of capital.
2) Bonds and CDs (the schedule-makers)
Bonds and CDs are the classic income instruments: you lend money; they pay you interest. If your main goal is
“I want cash flow I can plan around,” fixed income is the most literal version of that.
One of the most practical approaches is bond ladderingbuying bonds or CDs with staggered maturities so money
comes due regularly. As each rung matures, you can spend it or reinvest it at current rates. This can help manage interest-rate
risk and create a more predictable stream of cash flow.
3) Options-based income (the modern cash-flow factory)
Options strategiesespecially covered call approachesgenerate income by collecting option premiums.
The investor sells (writes) call options and gets paid a premium up front. In exchange, they give up some upside if markets rally
above the option’s strike price. That premium can be distributed monthly in many fund structures.
The appeal is obvious: you may be able to generate higher distributable cash flow than dividends alone.
The trade-off is also obvious once you say it out loud: you are literally selling away a portion of future upside potential.
That may be a reasonable bargain for some goals. It may be a lousy bargain for others.
How Options Income Can Produce Monthly Distributions (Without Requiring You to Become an Options Wizard)
If you’ve never touched options and would like to keep it that way, you’re not alone.
Options-based income ETFs exist partly because many investors want the potential cash-flow benefits without managing trades
themselves.
At the simplest level, here’s what’s happening:
- The strategy holds equities (often an index-like basket).
- It sells call options (and sometimes uses puts, depending on the approach).
- The option premiums collected become a cash-flow source.
- That cash flow can be distributed to shareholders, often monthly.
The “monthly income” feature is not magic. It’s math and market structure. The premium is real cash flow.
But the market doesn’t hand you premium for free; it charges you in the form of capped upside, strategy complexity,
and the possibility that the strategy underperforms in roaring bull markets.
Covered calls: the trade in plain English
Think of it like renting out the upside of your portfolio. You get paid rent (premium). If the market doesn’t explode upward,
you keep the rent. If it does explode upward, you don’t fully participate because you sold someone else the right to that upside
above a certain level.
In flat-to-choppy markets, that rent can look fantastic. In strong bull markets, you may feel like the only person at the party
who left early because you “had work in the morning.”
The Invesco “Income Advantage” Angle (And Why Design Details Matter)
The episode highlights the idea that not all option-income funds are built the same. Two products can both say
“monthly income,” yet behave very differently depending on:
- How much upside is sold (coverage ratio)
- How strikes are selected
- Whether the strategy uses calls only or calls and puts
- How the options exposure is implemented (direct options vs. notes/structures)
- How distributions are sourced and managed over time
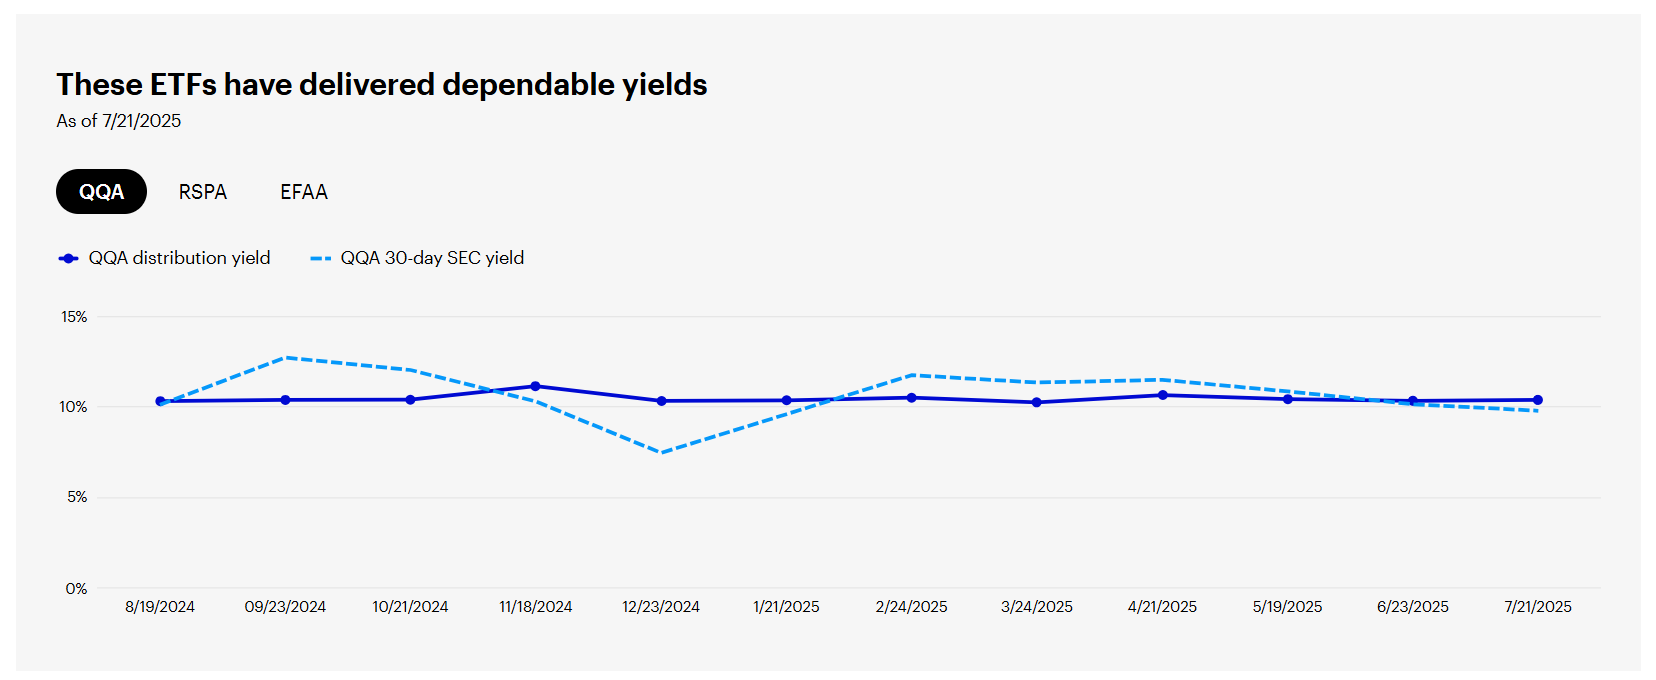
Invesco’s framing (as discussed in public materials tied to the episode topic) emphasizes targeting a more consistent yield by
actively adjusting strike prices as volatility changes and using both calls and puts to balance market participation and yield
trade-offs. The point isn’t that one approach is universally “best.” It’s that income strategies are engineered,
and the engineering choices show up in results.
If you’ve ever looked at two “high income” funds and wondered why one keeps up better in rallies while the other pays more but
lags over time, congratulationsyou’ve discovered that the label on the front of the can is not the whole ingredient list.
A Practical Framework for Creating Monthly Income (Without Building a Portfolio of Financial Riddles)
If your goal is monthly income, consider building a system that doesn’t depend on any single cash-flow source.
A simple, common-sense framework looks like this:
Layer 1: The “paycheck” layer
This layer is designed to fund near-term spending needs with higher reliability:
- Cash reserves for immediate needs
- Short-term bonds/CDs
- A bond ladder to create scheduled liquidity
You’re not trying to win the market with this layer. You’re trying to avoid selling risk assets at the worst possible time
just to pay normal-life expenses.
Layer 2: The “growth and inflation” layer
This is your equity exposurethe part that (historically) has done most of the heavy lifting against inflation over long periods.
It can be broad index exposure, diversified funds, or a thoughtfully built mix.
The income you take from this layer might come from dividends, periodic rebalancing, or strategic withdrawals rather than
relying solely on yield.
Layer 3: The “income enhancer” layer (optional, and optional means optional)
This is where tools like option-income strategies might liveif they fit your goals, your risk tolerance, and your tax situation.
The enhancer layer can help support cash flow, but it should not be the only pillar holding up your monthly spending.
In other words: build a table with four legs, not a unicycle with a great distribution yield.
A Worked Example (Numbers for Illustration, Not Instructions)
Imagine a $750,000 portfolio and a goal of $3,000 per month ($36,000 per year) in cash flow.
That’s a 4.8% annual spending rate on the original balance. Whether that’s sustainable depends on many variables:
market returns, inflation, taxes, time horizon, and how flexible spending is.
A “common sense” build might look like:
- 12 months of spending in cash-like instruments (so you can pay bills without forced selling)
- 2–5 years of spending needs in a bond ladder (staggered maturities for planned liquidity)
- A diversified equity core for long-term growth
- A smaller sleeve of income-enhancing strategies if desired (and understood)
The monthly income might come from a blend:
- Bond/CD interest paid on a schedule
- Dividends from equities
- Optional distributions from an options-income sleeve
- Periodic sales/rebalancing when appropriate
The key idea: you are not forced to make your spending equal your portfolio’s yield.
You can design the portfolio for risk and diversification first, then create a spending system that pulls cash flow from multiple
sources.
What Could Go Wrong (A Non-Exhaustive List, Because Markets Are Creative)
1) Yield chasing changes your risk without asking permission
High-yield assets can carry higher default risk (in credit), higher volatility (in equities), or higher structural complexity (in derivatives).
If you upgrade yield and accidentally upgrade risk, your monthly income plan can become a monthly stress plan.
2) Options income can lag badly in strong bull markets
Selling calls often means you’re trading some future upside for current premium. That trade may be fine if your priority is cash flow.
It may be painful if you later realize you wanted growth more than you wanted a “distribution headline.”
3) Distribution rates can mislead
A big distribution doesn’t automatically mean big returns. A fund can pay a large distribution and still have a mediocre (or negative)
total return if the underlying holdings decline or if the structure is giving you back your own money in a tax-structured way.
Read how distributions are sourced. Don’t just admire the yield number like it’s a trophy.
4) Taxes can surprise you
Dividends might be qualified or ordinary. Option premiums and certain distributions may have their own tax treatment.
The amount that hits your bank account is not the same as the amount you keep after taxes.
(Yes, this is the part where your CPA becomes the most important influencer in your life.)
5) The real villain: sequence-of-returns risk
If markets drop early in retirement (or early in your “living on the portfolio” phase), selling assets to fund spending can permanently
damage long-term sustainability. That’s why having a paycheck layer and a liquidity plan matters more than finding the world’s most
exciting yield.
How to Stress-Test Your Monthly Income Plan
Before you commit to any “monthly income” setup, run it through a simple checklist:
- Can I explain where the cash flow comes from? Dividends? Interest? Option premiums? Something else?
- What am I giving up to get it? Upside? Liquidity? Credit quality? Simplicity? Tax efficiency?
- How does it behave in a down market? Not just “does it pay,” but “does my principal hold up?”
- What’s my backup plan? If distributions fall, what gets adjustedspending, withdrawals, or assets sold?
- How does this fit with diversification? Income shouldn’t come with a side order of accidental concentration.
If any answer is “I’m not sure, but the yield is awesome,” pause. That’s your money trying to text you from the future.
Experience Section: What the “Monthly Income” Journey Often Feels Like (The Real-World Version)
People usually imagine the monthly-income phase as a calm, spreadsheet-driven glide path: distributions arrive, bills get paid,
the portfolio behaves, everyone remains emotionally stable forever. That last part is adorable.
In reality, the most common experience investors describe is not a math problemit’s a habit change.
For years, you’re trained to think like an accumulator: “Buy. Hold. Reinvest. Ignore the noise.” Then you flip a switch and suddenly
the questions become: “Is the cash here yet?” “Why is this month’s distribution smaller?” “Did something break?” “Should I sell now?”
One experience many income-focused investors report is that the first few months feel weirdly emotional, even when the plan is sound.
A portfolio that drops 8% in a quarter might have felt like normal market weather during accumulation. But when you’re using it to
fund living expenses, that same drop can feel personallike the market is reviewing your life choices in real time.
That’s exactly why “monthly income” strategies are so tempting: they offer structure, and structure can calm nerves.
Another common experience: investors discover the difference between consistent deposits and consistent outcomes.
Options-income strategies, dividend funds, and bond ladders can help create regular deposits. But outcomes still depend on the market environment.
In a flat market, an options-income sleeve may feel like a genius move: cash arrives, the portfolio doesn’t get too wild, and you can
pretend you outsmarted capitalism. In a strong bull market, the same sleeve might feel like you paid for a front-row seat and then
voluntarily watched the concert from the parking lot because the snacks were cheaper.
There’s also a very practical experience that shows up quickly: cash management becomes a hobby.
People start setting up a “paycheck pipeline”a checking account that receives distributions, a buffer account that holds one to three
months of expenses, and an investing account that refills the buffer on a schedule. This alone can reduce stress because your day-to-day
life stops depending on the market’s mood that week.
Taxes are another “experience” that tends to arrive uninvited. Investors often report surprise at how different income streams are
taxed, and how the same portfolio can feel wildly different after-tax depending on account type and distribution character.
The lesson they learn (sometimes painfully) is that income planning is not just investment selection;
it’s also coordinationbetween holdings, accounts, withdrawal order, and tax rules.
Finally, the most valuable experience people describe is a mindset shift:
they stop trying to make the portfolio “never go down,” and start trying to make the plan “never fall apart.”
That’s the real win. A solid monthly income plan isn’t one that promises perfect stability. It’s one that builds enough diversification,
liquidity, and flexibility that you can keep paying yourself through different market seasonswithout panicking, without improvising,
and without turning your retirement (or income phase) into a second full-time job.
Bottom Line: Common Sense Monthly Income Is Built, Not Found
The big message behind Talk Your Book: Creating Monthly Income From Your Portfolio isn’t that there’s one magical product that
turns markets into a paycheck machine. It’s that income is a design problem.
You can create monthly cash flow from dividends, from bond ladders, from options income, ormost oftenfrom a thoughtful mix.
The smartest plans focus on diversification first, then build a spending system that doesn’t require perfect market behavior.
Because markets are not perfect. They are talented, dramatic, and occasionally feral.
If you want “monthly income,” aim for a plan that still works when yields change, volatility spikes, or bull markets make you question
your life choices. That’s wealth of common sense in action.