Every investor loves a great trade story. Someone spots a huge opportunity, places a bold bet, waits while everyone else calls them ridiculous, and thenboomthe market agrees. Cue the confetti, the magazine covers, and at least one nephew asking, “So… what stock should I buy?”
But the real value of studying the most profitable trades is not copying them. By the time a legendary trade becomes legendary, the easy money has usually left the building, taken the elevator, and bought a beach house. The better goal is to understand the thinking behind the trade: how investors identify imbalance, manage risk, separate emotion from analysis, and hold long enough for an idea to mature.
The Financial Samurai approach to investing often emphasizes practical wealth-building, common sense, diversification, and the ability to think independently. That mindset is useful when studying famous profitable trades because it keeps us from worshiping luck. Great trades are rarely just lucky guesses. They are usually built from preparation, patience, position sizing, and the courage to act when the crowd is busy screaming into a pillow.
Why Profitable Trades Teach Better Lessons Than Perfect Theories
Investment textbooks are useful, but markets do not always behave like tidy classroom diagrams. Real trades happen in messy environments filled with fear, greed, politics, interest rates, earnings surprises, and investors who suddenly decide that a stock is worth 40% more because someone on television used the word “revolutionary.”
The most profitable trades teach us because they connect theory with behavior. Warren Buffett’s long-term investments show the power of buying excellent businesses and letting compounding do the heavy lifting. George Soros’s famous British pound trade shows how macro imbalances can become opportunities when a policy is unsustainable. John Paulson’s subprime mortgage trade shows how independent research and asymmetric payoff can turn skepticism into extraordinary returns.
These examples are dramatic, but the underlying lessons are surprisingly practical for everyday investors. You do not need a hedge fund office, a Bloomberg terminal, or a dramatic stare out of a Manhattan window. You need a repeatable process.
Lesson 1: Every Market Event Creates Winners and Losers
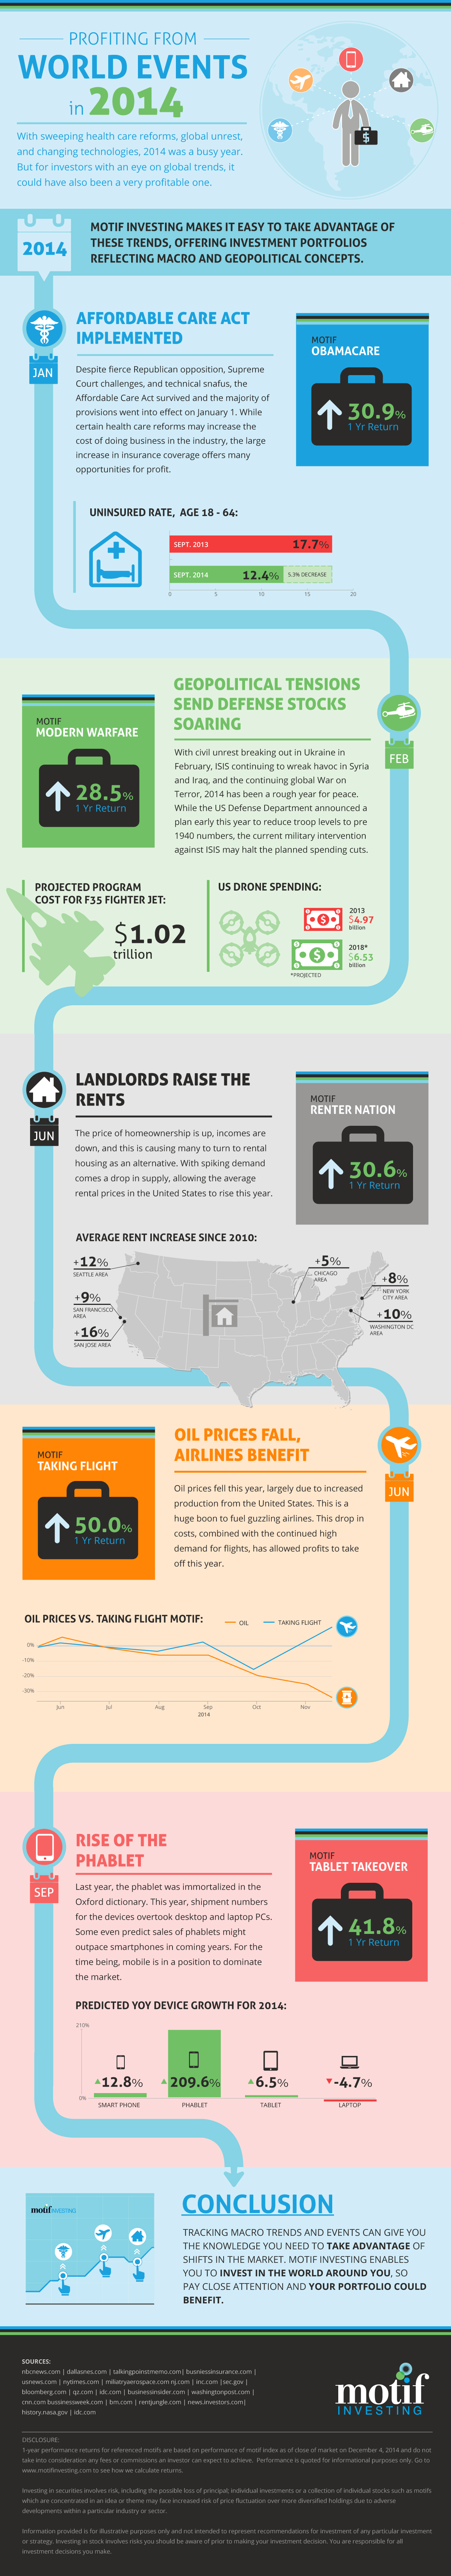
One of the smartest ideas from Financial Samurai’s discussion of profitable trades is the “yin and yang” of investing. When one asset, industry, or trend gets hurt, another may benefit. Markets are connected. A falling oil price can hurt energy producers but help airlines, delivery companies, and consumers. Rising interest rates can pressure speculative growth stocks but support certain lenders, money market yields, and investors with cash ready to deploy.
This does not mean every bad headline is secretly a treasure map. Sometimes bad news is just bad news wearing an expensive suit. But profitable investors train themselves to ask a second question: “Who benefits?”
Example: Lower Input Costs
If lumber, steel, or semiconductor prices decline, companies that rely heavily on those inputs may see margins improve. Homebuilders, automakers, manufacturers, and electronics companies can all be affected by changes in raw material costs. A beginner may only see a commodity chart falling. A more thoughtful investor sees a possible margin story forming downstream.
Example: Fear Moving Money
During market panic, investors often flee risky assets and move into perceived safer assets. This can affect bonds, defensive stocks, cash-like instruments, and high-quality companies with stable earnings. The lesson is not to celebrate panic. The lesson is to understand capital flow. Money rarely disappears; it moves.
Lesson 2: Remove Personal Emotion From Investment Analysis
Many profitable trades come from seeing opportunity where other people see only an argument. Political changes, healthcare reform, housing shortages, energy transitions, artificial intelligence, and demographic shifts can all create investable themes. Investors often miss them because they are too busy being emotionally right.
You may dislike a policy and still recognize that certain companies could benefit from it. You may be annoyed by rising rents and still understand that apartment owners, real estate investment trusts, property technology firms, or homebuilders may profit from housing demand. The market does not care whether we approve of a trend. It cares whether cash flows change.
This is uncomfortable, because investing forces us to separate identity from analysis. Your portfolio is not a bumper sticker. It is a machine designed to help you reach financial goals. If a theme is durable, legal, understandable, and priced attractively, it deserves analysiseven if it does not match your dinner-table rant.
Lesson 3: Ideas Are Cheap; Execution Is Expensive
Everyone has investment ideas. Your barber has three. Your cousin has nine, and one of them involves a coin with a dog wearing sunglasses. The difference between an idea and a profitable trade is execution.
Profitable investors define the idea clearly. They ask what must happen for the investment to work, what could go wrong, how much downside they can tolerate, and how long the thesis may take. They also decide whether to express the idea through a single stock, a basket of stocks, an ETF, bonds, real estate, private investments, or simply by adjusting asset allocation.
For most investors, baskets are often safer than hero picks. A single company can suffer from fraud, poor management, lawsuits, debt problems, or one executive who thinks “strategic pivot” means lighting shareholder money on fire. A diversified basket reduces company-specific risk while still giving exposure to a theme.
Lesson 4: Never Invest in What You Do Not Understand
One timeless investment lesson is simple: if you cannot explain the investment in plain English, you probably should not own much of it. This does not mean you must understand every accounting footnote or bond convexity calculation. It means you should know what you own, why you own it, how it makes money, what could make it lose money, and when you would change your mind.
Warren Buffett often describes this as staying within your circle of competence. That circle can expand over time, but pretending to understand something is dangerous. Markets are excellent lie detectors. They eventually find the investors who confused confidence with knowledge.
This is especially important with complex products such as options, leveraged ETFs, private funds, structured notes, cryptocurrency projects, and highly speculative stocks. Complexity is not automatically bad, but it should come with humility. If the investment has three layers of derivatives and a 90-page document, do not treat it like a savings account with a tuxedo.
Lesson 5: The Best Trades Often Have Asymmetric Payoffs
Many legendary trades were not attractive because the investor knew the future with perfect certainty. They were attractive because the potential reward was much larger than the carefully measured risk. That is asymmetric investing.
George Soros’s famous bet against the British pound in 1992 is often described this way. The trade was based on the belief that the pound was overvalued within the European Exchange Rate Mechanism and that the Bank of England could not defend it forever. The key lesson is not “go short currencies.” The lesson is that structural pressure can create opportunities when the market price depends on a fragile assumption.
John Paulson’s trade against subprime mortgages before the financial crisis also reflected asymmetry. The housing market looked stable to many investors, but some mortgage securities were vulnerable if defaults rose. Paulson’s team used credit default swaps to express a bearish view. The trade was risky, controversial, and difficult to hold, but the payoff became enormous when the housing market cracked.
For everyday investors, asymmetry may look much simpler. It might mean buying a high-quality stock during a panic when the long-term business remains strong. It might mean investing consistently during bear markets when fear has lowered prices. It might mean starting a side business where the upfront cost is small but the upside is meaningful. The form changes, but the principle stays the same: risk a manageable amount for a potentially meaningful reward.
Lesson 6: Patience Turns Good Trades Into Great Investments
Some trades become famous because they work quickly. Many of the best investments, however, become powerful because they are allowed to compound. Buffett’s greatest successes came not from frantic trading but from owning strong businesses for long periods. Coca-Cola, American Express, GEICO, and Apple all reflect the same broad idea: quality plus time can become a money-printing machine, minus the illegal part.
Patience sounds easy until a stock falls 20%, a recession appears, or your neighbor brags about doubling money in something you have never heard of. The challenge is not knowing that patience matters. The challenge is practicing patience while markets try to make you feel foolish.
That is why investors need a written plan. A plan helps you distinguish between volatility and a broken thesis. If your reason for buying remains intact, volatility may be uncomfortable but tolerable. If the thesis is broken, patience becomes stubbornness wearing a fake mustache.
Lesson 7: Risk Management Is the Real Superpower
People love to study the upside of famous trades. They rarely spend enough time studying survival. Yet survival is what allows compounding to continue. One disastrous trade can erase years of progress. As the old market joke goes, there are bold traders and old traders, but bold old traders are rare creatures, like unicorns with spreadsheets.
Risk management includes diversification, position sizing, rebalancing, cash reserves, and knowing when not to play. It also means accepting that even smart ideas can fail. A great thesis can be early. A cheap stock can get cheaper. A macro imbalance can persist longer than your patience, margin account, or marriage.
This is why most investors should keep their financial foundation boring. Broad index funds, diversified ETFs, retirement accounts, emergency savings, and low-cost investing may not impress people at parties, but they work. Once the foundation is strong, a smaller portion of the portfolio can be used for active ideas, individual stocks, thematic investing, or higher-risk opportunities.
Lesson 8: Market Timing Is Usually a Trap
The most profitable trades can make market timing look easy. It is not. In fact, trying to jump in and out of the market often leads investors to miss the best recovery days, which can severely reduce long-term returns. Many of the market’s strongest days occur near its worst days, when emotions are hottest and discipline is weakest.
A better strategy for most investors is time in the market, not perfect timing of the market. Dollar-cost averaging can help because it turns investing into a habit instead of an emotional wrestling match. When prices fall, regular contributions buy more shares. When prices rise, the existing portfolio benefits. It is not glamorous, but neither is brushing your teeth, and dentists seem pretty committed to that idea.
Lesson 9: Rebalancing Keeps Winners From Taking Over
A profitable trade can become dangerous if it grows too large. This is one of the least discussed problems in investing: success changes your risk profile. If one stock, sector, or asset class explodes higher, your portfolio may become more concentrated than intended.
Rebalancing forces you to review your portfolio and bring it back toward your target allocation. Sometimes that means trimming winners. Sometimes it means adding to underperforming areas. The point is not to predict the next six months perfectly. The point is to prevent your portfolio from becoming an accidental bet you would never intentionally make.
This is also where tax planning matters. Selling winners in taxable accounts can create capital gains. Investors should consider tax impact, account type, time horizon, and transaction costs before making changes. A good investment decision can still be improved by smart tax awareness.
How Everyday Investors Can Apply These Lessons
You do not need to short a currency, analyze mortgage derivatives, or buy a company before it becomes a global titan to use the lessons from profitable trades. You can apply them in a practical way:
Build a Core Portfolio First
Use diversified, low-cost funds as the base of your financial plan. This creates stability and helps reduce the temptation to gamble with money you cannot afford to lose.
Keep an Opportunity List
Write down themes you understand: aging populations, housing shortages, artificial intelligence, cybersecurity, energy infrastructure, healthcare innovation, or consumer brands with pricing power. Then study how to invest in them responsibly.
Size Speculative Bets Carefully
If you enjoy active investing, limit it to a percentage of your portfolio that will not ruin your financial life. A 10% experimental sleeve can be exciting. A 90% experimental sleeve is not a strategy; it is a Vegas bachelor party with an app login.
Review the Thesis, Not the Price Alone
A falling price does not automatically mean an investment is bad. A rising price does not automatically mean you are brilliant. Review the original thesis. Are revenues, margins, competitive advantages, balance sheet strength, or macro conditions improving or deteriorating?
Common Mistakes to Avoid
The first mistake is confusing a famous investor’s trade with your own risk profile. Soros, Paulson, and Buffett operated with resources, research teams, experience, and time horizons that most individuals do not have. Copying the surface-level trade without the underlying process is like wearing a chef’s hat and assuming dinner will cook itself.
The second mistake is chasing performance after the easy money has already been made. If a stock, sector, or theme has become the internet’s favorite topic, future returns may already be priced in. Great investing often feels uncomfortable because the best prices tend to appear when enthusiasm is low.
The third mistake is ignoring liquidity. Some investments are easy to buy and hard to sell. Private investments, thinly traded securities, and complex funds may lock up capital or become difficult to value. Liquidity matters most when you suddenly need it.
The fourth mistake is using leverage casually. Borrowed money can magnify returns, but it can also turn a temporary decline into a permanent loss. Leverage is like hot sauce: a little may improve the meal, but drinking the bottle is a medical event.
Additional Experience: What Profitable Trades Teach in Real Life
One of the most useful experiences an investor can have is watching a good idea test their emotions. Imagine identifying a strong business during a broad market sell-off. The company has low debt, healthy cash flow, and products customers continue buying. You invest because the valuation finally looks reasonable. Then the stock falls another 15%.
This is where investing becomes personal. Your spreadsheet says one thing; your stomach says another. You start checking the price too often. You read bearish articles. You wonder whether you missed something. This is the emotional toll hidden inside every profitable trade story. The final chart may look smooth, but living through the trade feels like riding a shopping cart downhill while holding coffee.
From experience, the best way to handle this is to write the investment thesis before buying. Include the reason for purchase, expected time horizon, risks, valuation range, and conditions that would make you sell. This document does not need to be fancy. A few paragraphs can save you from making decisions based on fear. When volatility hits, you can return to your notes and ask, “Has the thesis changed, or am I just uncomfortable?”
Another practical experience is learning that cash is not laziness. Cash can be optionality. Investors often feel pressure to be fully invested at all times, but having some cash available during downturns can provide confidence and flexibility. The goal is not to hoard cash forever. The goal is to avoid being forced to sell quality assets at bad prices and to have dry powder when opportunity appears.
Profitable trades also teach humility. Sometimes an investment works for the wrong reason. You may buy because of revenue growth, but the stock rises because interest rates fall. You may sell because valuation looks expensive, only to watch the business continue compounding for years. The market has a way of reminding investors that being profitable and being correct are not always identical twins.
A useful habit is keeping an investment journal. Record buys, sells, mistakes, and emotional reactions. Over time, patterns appear. Maybe you sell winners too early. Maybe you double down on losers without enough evidence. Maybe you chase hot sectors after they peak. Maybe your best returns come from boring companies you almost ignored. This feedback is priceless because it turns market experience into self-knowledge.
The biggest experience-based lesson is that wealth usually comes from combining offense and defense. Offense means seeking growth, buying assets, studying opportunities, and acting when expected returns are attractive. Defense means diversification, emergency funds, insurance, low debt, and avoiding catastrophic mistakes. Investors who only play offense may get rich quickly and lose it faster. Investors who only play defense may preserve money but miss growth. The sweet spot is a system that lets you stay in the game long enough for compounding to work.
Finally, the most profitable trade is not always the one with the highest return. Sometimes it is the trade that keeps you disciplined, improves your process, and helps you sleep at night. A portfolio that supports your life is better than a portfolio that turns every Tuesday into a blood-pressure experiment. The goal is not to win every trade. The goal is to build lasting wealth with intelligence, patience, and just enough humor to survive the next market correction.
Conclusion
The most profitable trades in history are exciting, but their real gift is education. They teach us to look for second-order effects, control emotions, understand what we own, respect risk, and let strong ideas compound. Financial Samurai’s practical message fits neatly here: spend time thinking before investing, build a diversified plan, and avoid chasing what you do not understand.
Great investors are not great because they predict everything. They are great because they prepare better, manage downside, and act decisively when odds are favorable. For regular investors, that means building a strong core portfolio, using active ideas carefully, rebalancing when needed, and remembering that the market rewards discipline far more often than drama.
Note: This article is for educational purposes only and should not be considered personalized financial advice. Investors should evaluate their own goals, time horizon, risk tolerance, tax situation, and financial circumstances before making investment decisions.