Choosing the right asset allocation sounds like something that should require a calculator, a wall of spreadsheets, and possibly a financial wizard wearing bifocals. In reality, it starts with a much simpler question: What do you need your money to do, and when do you need it to do that?
Asset allocation is the way you divide your investment portfolio among different types of assets, usually stocks, bonds, cash, and sometimes real estate, commodities, or alternative investments. It is one of the most important decisions an investor makes because it influences both potential return and risk. Pick too aggressively, and market drops may keep you awake at 2:13 a.m. refreshing your account balance like it owes you an explanation. Pick too conservatively, and inflation may quietly nibble away at your purchasing power like a raccoon in the pantry.
The good news? You do not need to predict the next hot stock, interest rate move, or market headline. A smart asset allocation strategy is built around your goals, time horizon, risk tolerance, cash needs, taxes, and ability to stay disciplined when markets misbehave.
What Is Asset Allocation?
Asset allocation is the process of spreading your money across asset classes. The major building blocks are:
- Stocks: Often used for long-term growth, but they can be volatile.
- Bonds: Usually provide income and stability, though they still carry interest rate and credit risk.
- Cash or cash equivalents: Useful for emergencies and short-term goals, but usually offers lower long-term growth.
- Real estate and alternatives: May add diversification, income, or inflation protection, but can be more complex, expensive, or illiquid.
Think of your portfolio like a road trip vehicle. Stocks are the engine, bonds are the suspension, cash is the spare tire, and diversification is the seatbelt. You may not need all of them in the same proportion, but you probably do not want to drive cross-country with only an engine and a dream.
Why Asset Allocation Matters More Than Stock Picking
Many investors spend too much time asking, “Which investment will perform best this year?” A better question is, “What mix of investments gives me a realistic chance of reaching my goal without making me panic-sell during a downturn?”
No asset class wins forever. Stocks may lead during expansionary periods, bonds may provide ballast during certain downturns, and cash can be a lifesaver when you need money immediately. The purpose of asset allocation is not to make every part of your portfolio perform perfectly. That is impossible. The goal is to create a mix that works together across different market environments.
Step 1: Start With Your Financial Goals
Your asset allocation should begin with your goals, not with market predictions. A portfolio for a 30-year retirement goal should not look the same as money needed for a house down payment in two years.
Short-Term Goals: 0 to 3 Years
If you need the money soon, preservation matters more than growth. Examples include an emergency fund, a car purchase, tuition due next year, or a home down payment. For these goals, cash, high-yield savings accounts, money market funds, Treasury bills, or short-term bonds may be more appropriate than a stock-heavy portfolio.
Medium-Term Goals: 3 to 10 Years
For goals several years away, you may be able to accept some investment risk, but not as much as you would for retirement decades in the future. A balanced mix of stocks and bonds can help you pursue growth while reducing the chance that a market downturn ruins your timeline.
Long-Term Goals: 10+ Years
For long-term goals such as retirement, stocks often play a larger role because they historically offer higher growth potential over long periods. However, long-term does not mean “all risk, all the time.” Even younger investors need an allocation they can emotionally handle.
Step 2: Understand Your Risk Tolerance
Risk tolerance is your comfort level with investment ups and downs. It is easy to say you are aggressive when the market is rising. The real test comes when your portfolio drops 20%, financial news gets dramatic, and your neighbor suddenly becomes an “expert” because he watched three videos about gold.
Ask yourself:
- How would I react if my portfolio lost 15% in a few months?
- Would I keep investing, freeze, or sell everything?
- Do I understand that higher potential returns usually come with higher volatility?
- Am I investing for growth, income, capital preservation, or a mix?
Risk tolerance has both emotional and financial sides. Emotional tolerance is how much volatility you can stomach. Financial risk capacity is how much risk your actual situation allows. A person with a stable job, no debt, and a 30-year time horizon may have higher risk capacity than someone retiring next year with limited savings, even if both say they are “comfortable with risk.”
Step 3: Match Allocation to Time Horizon
Your time horizon is the amount of time before you expect to use the money. The longer your time horizon, the more time your portfolio has to recover from downturns. This is why younger retirement investors often hold more stocks, while retirees often include more bonds and cash.
Here are simple example allocations. These are not recommendations, but useful starting points:
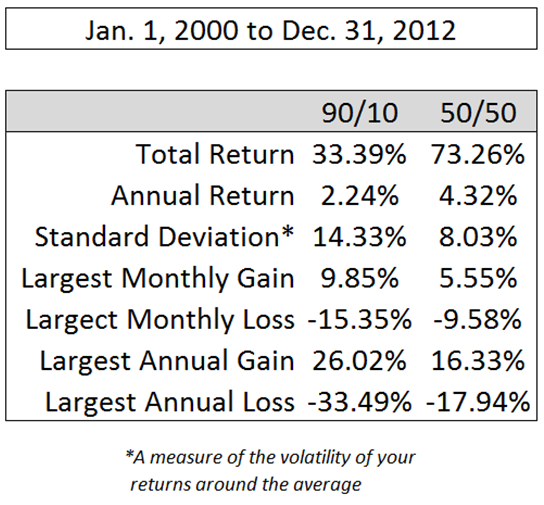
- Aggressive allocation: 80% stocks, 20% bonds/cash. Designed for long-term growth and higher volatility.
- Moderate allocation: 60% stocks, 40% bonds/cash. A common balanced approach for investors seeking growth with some stability.
- Conservative allocation: 40% stocks, 60% bonds/cash. More focused on stability, income, and lower volatility.
The best allocation is not the one that looks impressive in a bull market. It is the one you can stick with when markets get rude.
Step 4: Diversify Inside Each Asset Class
Asset allocation decides how much you put into broad categories. Diversification decides how you spread money within those categories.
For stocks, diversification may include U.S. large-cap stocks, U.S. small-cap stocks, international developed markets, and emerging markets. For bonds, it may include U.S. government bonds, investment-grade corporate bonds, short-term bonds, Treasury Inflation-Protected Securities, and possibly municipal bonds for taxable accounts.
Owning one stock is not diversification. Owning five technology stocks is also not true diversification; it is more like wearing five shirts but no pants. A diversified portfolio spreads risk across companies, sectors, countries, and asset types.
Step 5: Consider Your Age, But Do Not Obey It Blindly
Traditional rules of thumb, such as subtracting your age from 100 or 110 to estimate your stock allocation, can be a rough starting point. For example, a 40-year-old using the “110 minus age” rule might hold about 70% in stocks. However, these shortcuts ignore important details such as income stability, pensions, spending needs, debt, health, family obligations, and personal comfort with volatility.
Age matters, but goals matter more. A 65-year-old with substantial savings and modest expenses may be able to hold more stocks than a 45-year-old who needs money soon for a business purchase or family obligation.
Step 6: Build Around Cash Needs
Before designing a fancy portfolio, make sure your basic cash needs are covered. An emergency fund can prevent you from selling investments at the worst possible time. Many households aim for three to six months of necessary expenses, though the right amount depends on job stability, dependents, insurance coverage, and income variability.
Cash is not exciting. Nobody brags at dinner about their emergency fund unless they enjoy being gently avoided. But cash gives you flexibility, and flexibility is underrated. It allows your long-term investments to stay invested when life throws a surprise bill, job change, or broken water heater into the plot.
Step 7: Factor in Taxes and Account Types
Asset allocation tells you what to own. Asset location tells you where to own it. This matters because different accounts are taxed differently.
In taxable brokerage accounts, investments that generate qualified dividends or long-term capital gains may receive different tax treatment than short-term gains or ordinary income. In tax-advantaged accounts such as traditional IRAs, Roth IRAs, and 401(k)s, taxes depend on the account type and withdrawal rules.
A common strategy is to place tax-inefficient investments, such as certain taxable bond funds or high-turnover funds, in tax-advantaged accounts when possible. More tax-efficient stock index funds may fit well in taxable accounts. However, tax planning can become complicated, so investors with larger portfolios or complex tax situations may benefit from professional advice.
Step 8: Watch Investment Costs
Costs quietly reduce returns. Expense ratios, advisory fees, trading costs, fund loads, and tax drag can all affect long-term results. A fund charging 0.80% annually may not sound expensive, but over decades the difference between low-cost and high-cost investments can become substantial.
This does not mean the cheapest investment is always the best. It means every fee should earn its place. Low-cost index funds and ETFs are popular because they offer broad diversification, transparency, and efficiency. Actively managed funds may have a role, but investors should understand what they are paying for and whether the strategy has a reasonable chance of adding value after costs.
Step 9: Rebalance Your Portfolio
Markets move, and your portfolio drifts. Suppose you start with a 60% stock and 40% bond allocation. If stocks have a strong year, your portfolio might become 70% stocks and 30% bonds. That may be riskier than you intended. Rebalancing means bringing your portfolio back to its target mix.
There are several ways to rebalance:
- Calendar rebalancing: Review your allocation once or twice a year.
- Threshold rebalancing: Rebalance when an asset class moves a set percentage away from its target.
- Cash-flow rebalancing: Use new contributions to buy underweighted assets instead of selling existing holdings.
Rebalancing can feel uncomfortable because it often means trimming what recently performed well and adding to what lagged. In other words, it asks you to behave like a disciplined investor instead of a performance-chasing squirrel. That is exactly why it helps.
Step 10: Adjust as Life Changes
Your asset allocation is not a tattoo. It should evolve when your life changes. Major events such as marriage, divorce, a new child, home purchase, career change, inheritance, retirement, or health issue may require a fresh look.
You should also revisit your allocation as a goal gets closer. A college fund for a child who is 16 should usually be more conservative than one for a child who is 3. A retirement portfolio at age 60 may need a different balance than it did at age 35.
Common Asset Allocation Mistakes
Going Too Aggressive After a Bull Market
Investors often become confident after markets rise. Unfortunately, buying more risk after a huge rally can leave you exposed when conditions change. Your allocation should be based on your plan, not recent performance.
Going Too Conservative After a Crash
Selling stocks after a major decline may feel safe, but it can lock in losses and make it harder to participate in recovery. If your portfolio was too risky, adjust thoughtfully rather than emotionally.
Ignoring Inflation
Cash feels safe because the balance does not bounce around. But inflation reduces purchasing power over time. For long-term goals, being too conservative can be risky in a different way.
Confusing Complexity With Quality
A portfolio does not need 37 funds, three dashboards, and a color-coded spreadsheet named “Operation Wealth Eagle.” Simple, diversified, low-cost portfolios can be very effective.
Example: Choosing an Allocation for Different Investors
Example 1: Maya, Age 28, Investing for Retirement
Maya has a stable job, no high-interest debt, and a retirement horizon of more than 30 years. She can tolerate volatility and does not plan to use the money soon. A stock-heavy allocation, such as 80% to 90% stocks and 10% to 20% bonds, may fit her long-term growth goal, assuming she can stay invested during downturns.
Example 2: David, Age 45, Saving for Retirement and College
David has two goals: retirement in about 20 years and college costs in six years. His retirement account may hold a moderate-growth allocation, perhaps around 70% stocks and 30% bonds. His college savings may be more conservative because the money is needed sooner.
Example 3: Linda, Age 63, Preparing to Retire
Linda wants income, stability, and some growth to help her portfolio last. She may prefer a balanced or moderately conservative allocation, such as 40% to 60% stocks with the rest in bonds and cash. She may also hold one to three years of expected withdrawals in safer assets to reduce the pressure to sell stocks during a downturn.
Should You Use a Target-Date Fund or Robo-Advisor?
If you want a simpler approach, a target-date fund or robo-advisor may help. A target-date fund automatically adjusts its asset allocation as the target retirement year approaches. Robo-advisors typically recommend and manage portfolios based on your goals, risk profile, and time horizon.
These tools can be useful, especially for investors who want automation. However, you should still understand the underlying allocation, costs, and assumptions. Not all target-date funds with the same date hold the same mix of assets.
A Practical Checklist for Choosing the Right Asset Allocation
- Define each financial goal clearly.
- Separate short-term, medium-term, and long-term money.
- Estimate how much risk you can emotionally and financially handle.
- Choose a stock, bond, and cash mix that matches the goal timeline.
- Diversify within each asset class.
- Use low-cost funds when possible.
- Consider taxes and account types.
- Rebalance at least annually or when allocations drift too far.
- Review your plan after major life changes.
- Do not let headlines become your portfolio manager.
Personal Experiences and Lessons From Choosing Asset Allocation
One of the most useful lessons about asset allocation is that the “right” portfolio is rarely the one that looks best on paper. It is the one a real person can actually live with. Many investors discover this only after their first serious market decline. During calm markets, an aggressive allocation can feel brilliant. During a downturn, the same allocation can suddenly feel like skydiving with a backpack full of soup.
A common experience is starting too aggressively because high stock returns look attractive. An investor may choose 90% or 100% stocks after reading that stocks have historically outperformed bonds over long periods. Mathematically, that may make sense for someone with decades to invest. Emotionally, it may be a different story. If a 25% decline causes that investor to sell, the allocation was too aggressive. The problem was not the market; the problem was a mismatch between the portfolio and the person holding it.
Another real-world lesson is that separate goals need separate allocations. Many people make the mistake of treating all money the same. Retirement money, emergency savings, and a home down payment may sit mentally in one big bucket called “my money,” but they have completely different jobs. Money needed in two years should not be exposed to the same volatility as money needed in thirty years. Creating separate buckets can make decisions clearer and reduce stress.
Investors also learn that rebalancing is easier to admire than to practice. When stocks are soaring, selling a portion to buy bonds can feel like leaving the party early. When stocks are falling, buying more can feel like volunteering to catch a falling piano. Yet rebalancing is valuable because it turns discipline into a process. Instead of asking, “What do I feel like doing today?” you follow a rule created when you were calm.
Taxes can also surprise investors. Someone may build a smart allocation but place every investment in the least efficient account. Over time, taxable distributions, short-term gains, and unnecessary trading can reduce results. Asset location does not need to be perfect, especially for beginners, but as portfolios grow, taxes become worth attention. A simple improvement, such as keeping highly tax-efficient funds in taxable accounts and less tax-efficient assets in retirement accounts, may help improve after-tax outcomes.
Finally, many investors eventually realize that simplicity is a strength. A portfolio with a total U.S. stock fund, total international stock fund, total bond fund, and cash reserve may be easier to manage than a complicated collection of overlapping funds. Complexity can create the illusion of control, but it can also make rebalancing harder and decision-making messier.
The best asset allocation is personal, durable, and understandable. It should help you move toward your goals without requiring constant tinkering. It should be aggressive enough to pursue growth, conservative enough to survive bad markets, and simple enough that you can explain it without needing a whiteboard. When your portfolio fits your life, you are less likely to panic, chase trends, or make expensive emotional decisions. That is when asset allocation stops being theory and becomes a practical tool for building wealth.
Conclusion
Choosing the right asset allocation is not about finding a perfect formula. It is about building a portfolio that matches your goals, timeline, risk tolerance, tax situation, and behavior. Stocks may drive long-term growth, bonds may add stability and income, and cash may protect short-term needs. The right mix depends on what you want your money to accomplish.
Start with your goals. Match each goal to a time horizon. Choose a diversified allocation you can stick with. Keep costs low, consider taxes, rebalance regularly, and update your plan when life changes. Do that, and you will already be ahead of many investors who are still trying to win the market’s daily guessing game.
Note: This article is for educational purposes only and should not be treated as personalized financial, tax, or investment advice. Consider speaking with a qualified financial professional before making major investment decisions.