Note: Body-only HTML, ready for copying and web publishing.
If you have ever looked at a condo listing, spotted a surprisingly reasonable mortgage payment, and then noticed an extra line that says HOA: $325/month, you have already met one of homeownership’s favorite plot twists.
HOA fees are regular payments made to a homeowners association. They are common in condos, townhome communities, and many planned neighborhoods with shared amenities or common property. In plain English, HOA fees are the money residents pool together so the neighborhood does not slowly transform into a cracked-sidewalk, dead-shrub, broken-gate reality show.
But here is the part that confuses buyers: what do HOA fees actually pay for? The answer is not always simple, because every community is different. One HOA fee may cover landscaping, trash pickup, and the pool. Another may cover building insurance, elevator repairs, exterior maintenance, water, sewer, and a reserve fund for future projects. And in some communities, the fee is relatively low because the association covers less. In others, the fee is higher because the association covers more.
This article breaks down what HOA fees are, what they usually pay for, what they usually do not pay for, why condo fees often run higher than single-family HOA dues, and how to tell whether a fee is fair or a flashing neon warning sign. Because before you buy into an HOA, you should know whether you are paying for a well-run communityor funding a future special assessment with all the charm of a surprise cavity.
What Are HOA Fees?
HOA fees, sometimes called HOA dues or association assessments, are mandatory payments homeowners make to the association that manages the community. If you buy in that neighborhood or building, paying the fee is usually not optional. It comes with the property, just like the mailbox, the driveway, and the realization that grass somehow grows faster the moment you become responsible for it.
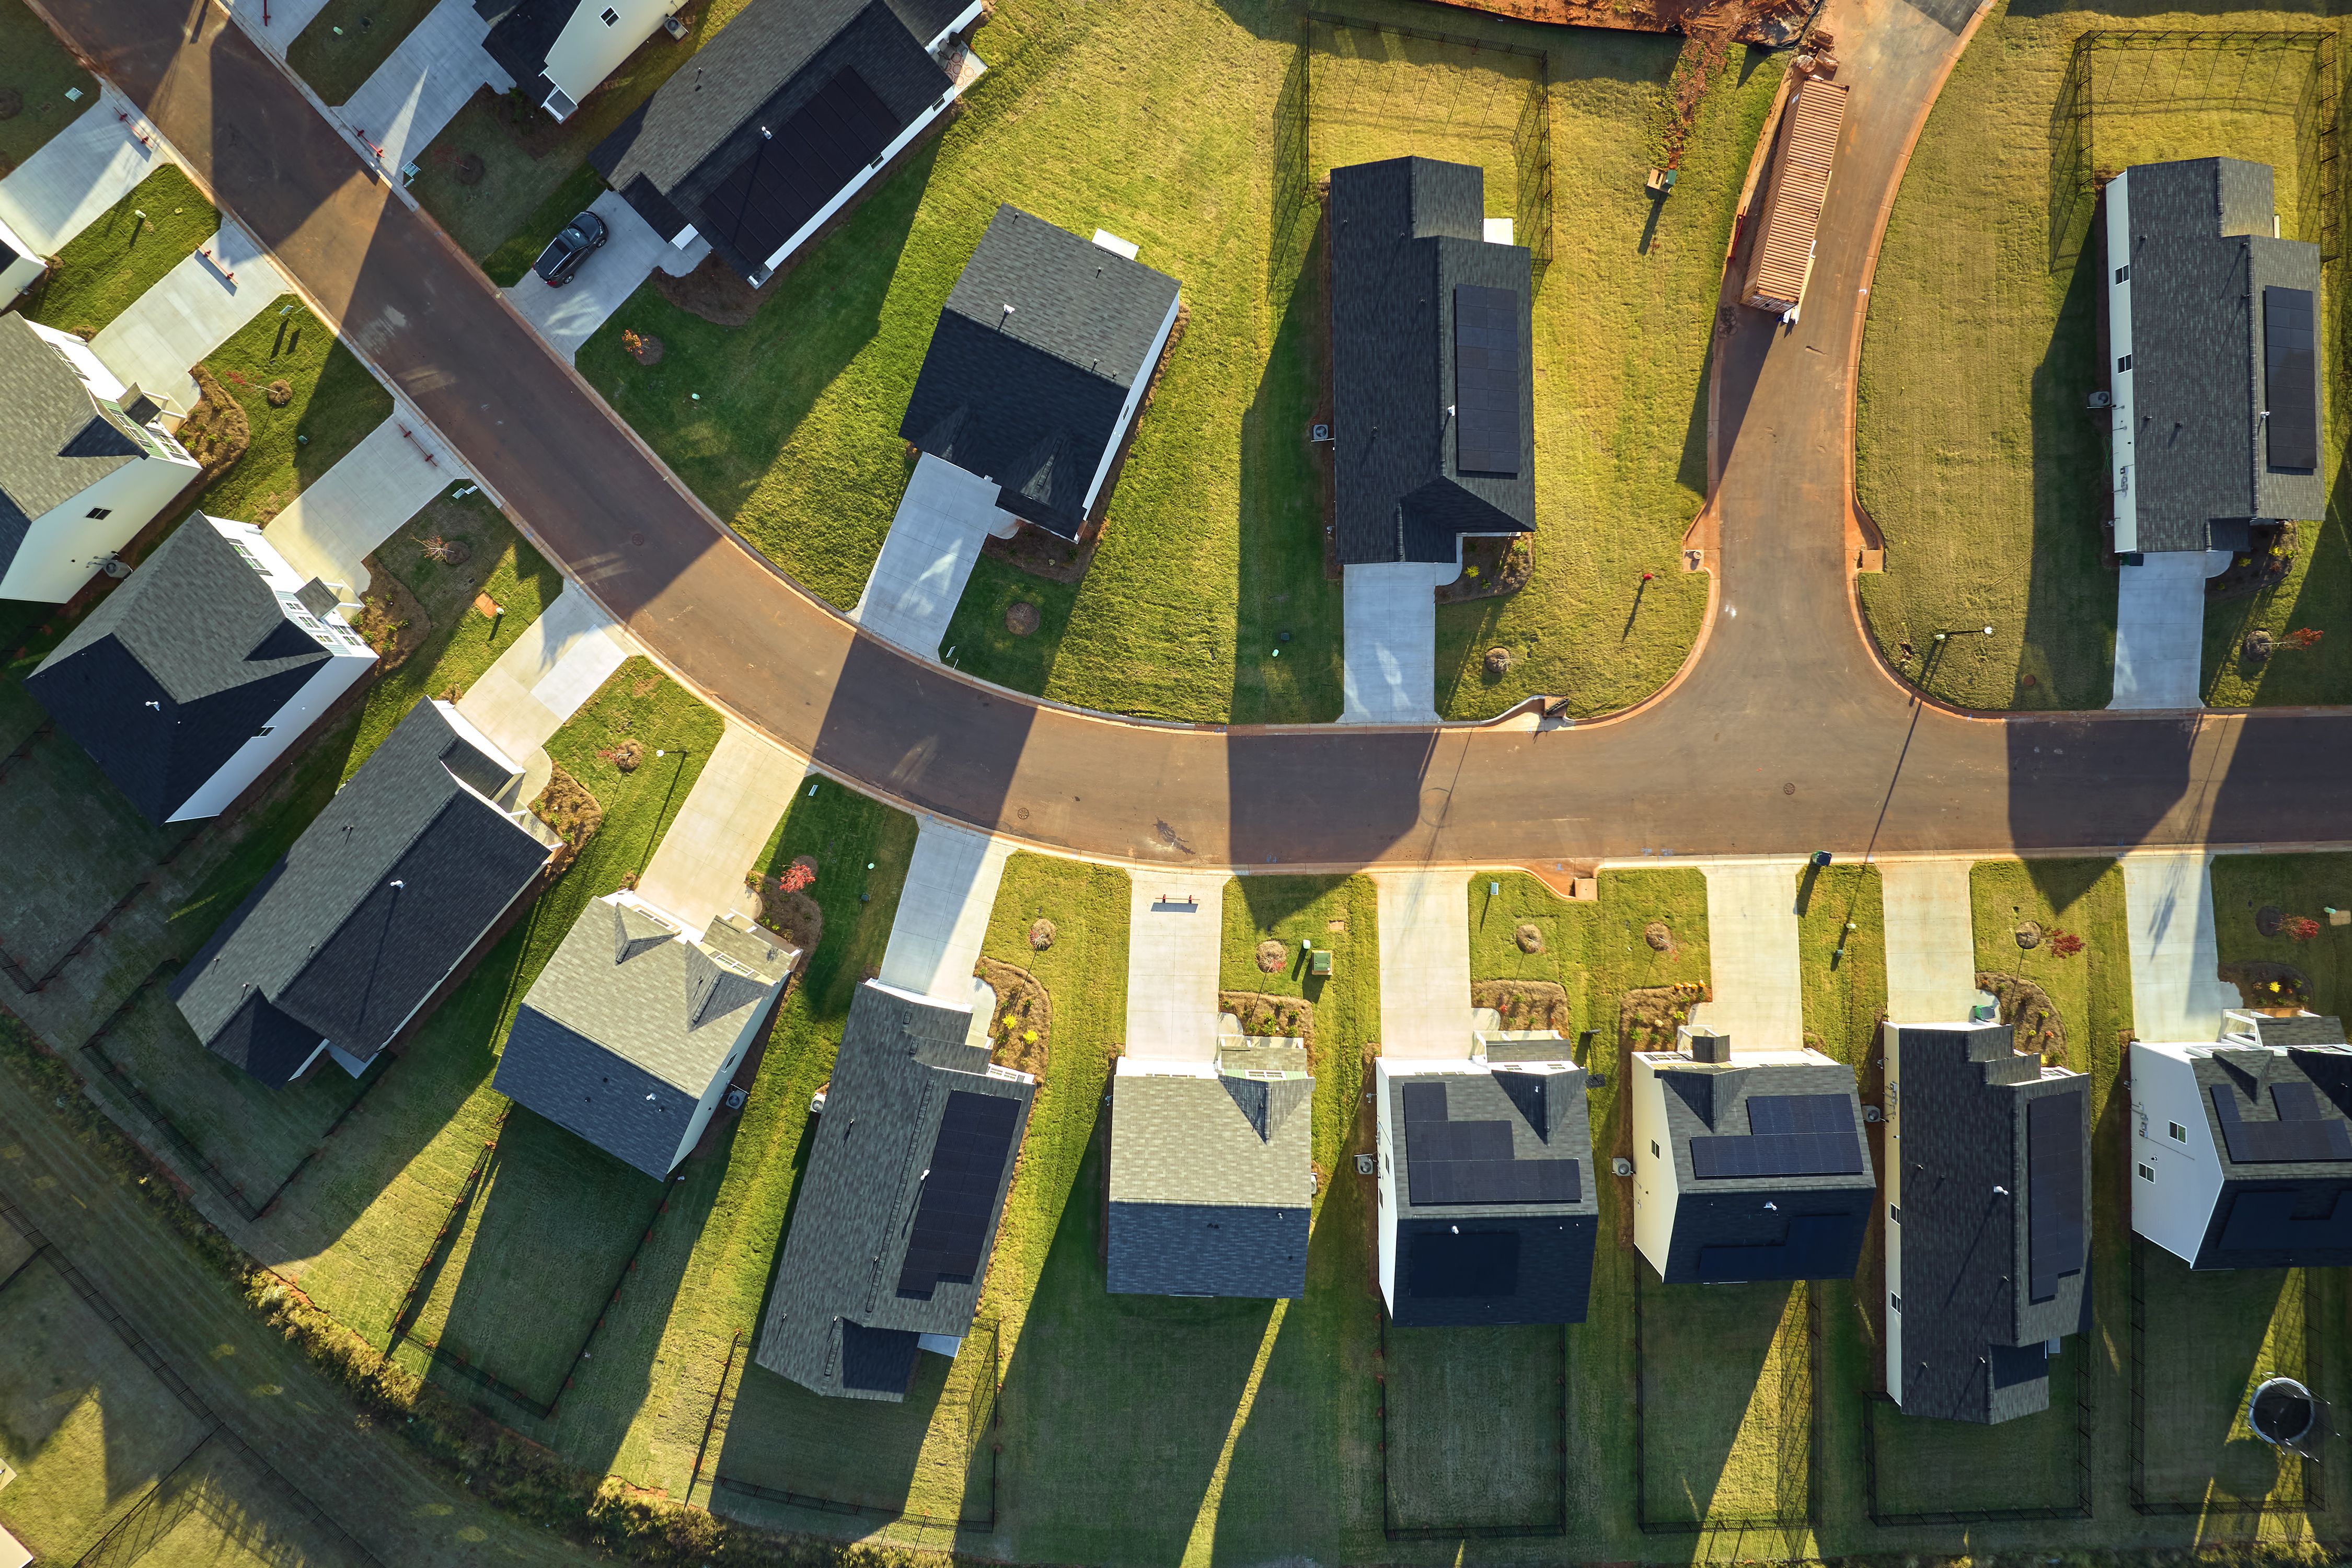
The association uses those funds to operate, maintain, insure, and repair shared parts of the community. In a condo building, that may include the roof, lobby, hallways, elevators, garage, and exterior walls. In a townhouse or planned subdivision, it may cover private roads, landscaped entrances, parks, playgrounds, gates, clubhouses, or neighborhood pools.
Some communities charge monthly. Others bill quarterly or annually. Either way, buyers need to treat HOA dues as part of their true housing cost, not as an afterthought.
How Much Are HOA Fees?
There is no single HOA fee that fits every property. Fees vary by region, property type, age of the community, labor costs, insurance costs, amenities, and how much maintenance the association is responsible for. A small neighborhood with a decorative entrance and a patch of grass will usually cost less to run than a high-rise condo with a staffed front desk, elevators, a fitness center, and a roof that seems personally offended by weather.
In many cases, fees may fall somewhere between modest and painful. National averages are useful for context, but they are not destiny. A lower-than-average fee is not automatically a bargain, and a high fee is not automatically a bad deal. The real question is this: what does the fee cover, and is the association financially healthy?
That question matters more than the sticker number. A $150 monthly fee might sound appealing until you discover the association has weak reserves, aging infrastructure, and a roof with the life expectancy of a carton of milk. Meanwhile, a $450 fee might be perfectly reasonable if it covers exterior maintenance, water, trash, master insurance, security, landscaping, and long-term reserves.
What HOA Fees Usually Pay For
The biggest misunderstanding about HOA fees is that people assume they vanish into a mysterious administrative cloud. In reality, most association budgets are fairly ordinary. The money usually goes into a few predictable buckets.
1. Common Area Maintenance
This is the classic use of HOA fees. The association maintains property owned or shared by the community as a whole. That can include:
- Landscaping and lawn care
- Sidewalks, paths, and private roads
- Community signage and entrances
- Hallways, stairwells, and lobbies
- Parking lots and garages
- Pools, clubhouses, playgrounds, and gyms
If the community looks tidy, trimmed, painted, and generally less chaotic than the average group project, HOA fees are probably helping make that happen.
2. Utilities for Shared Spaces
Some HOA budgets pay for utilities tied to common property. That may include electricity for hallway lights, irrigation systems, pool equipment, gate systems, and clubhouse power. In some condos or attached communities, HOA dues may also include water, sewer, trash, or even limited cable or internet. This is why the phrase “what does the HOA include?” matters so much. It can change the true value of the fee.
3. Insurance
Many associations carry a master insurance policy for common areas and shared structures. In a condo building, that can be a major expense. The policy often covers parts of the building exterior, roofs, shared walls, lobbies, and liability in common spaces. It does not usually replace the need for the homeowner’s own policy, especially for the interior of the unit, personal belongings, or personal liability.
This is one reason condo HOA fees are often higher than fees in single-family neighborhoods. There is simply more shared structure to insure and maintain.
4. Management and Administrative Costs
Someone has to collect payments, pay vendors, track contracts, organize records, prepare budgets, and answer homeowner questions ranging from “When is the pool opening?” to “Why can’t I paint my garage neon orange?” In many communities, HOA dues help pay for:
- Professional management companies
- Accounting and bookkeeping
- Legal compliance
- Office, mailing, and software expenses
- Security or front-desk staffing in some buildings
Administrative costs are not glamorous, but they are part of keeping the association functional and compliant.
5. Repairs and Routine Upkeep
HOA fees often fund ongoing repairs to shared property. That might include fixing a gate motor, patching private roads, servicing elevators, repainting common hallways, replacing pool furniture, or repairing a clubhouse HVAC system. Small repairs happen constantly in shared communities. The budget has to absorb them without collapsing into panic.
6. Reserve Funds for Future Big-Ticket Costs
This is the part smart buyers should pay close attention to. A portion of HOA fees may go into a reserve fund, which is savings for future major repairs and replacements. Think roofs, siding, pavement, elevators, plumbing systems, exterior paint, pool resurfacing, or large mechanical systems.
Healthy reserves are a sign the association is planning ahead. Weak reserves can be a sign that the community has been keeping dues artificially low, which sounds fun until the bill for a major repair lands in your lap wearing the disguise of a “special assessment.”
What HOA Fees Usually Do Not Pay For
HOA fees do not usually cover everything related to your home. Homeowners still have personal financial responsibilities, and they can be substantial.
In most communities, HOA dues do not pay for:
- Your mortgage payment
- Your property taxes
- Your personal homeowners or condo insurance policy
- Interior repairs inside your unit or house, unless the governing documents say otherwise
- Your appliances, flooring, cabinets, and personal belongings
- Maintenance of features that belong only to you
This is why buyers should never assume that a higher HOA fee means “maintenance-free” living in the absolute sense. It may mean less exterior responsibility, but it rarely means zero personal responsibility. The HOA may handle the roof above you, while you still handle the dishwasher below it that picked this week to become dramatic.
Why Condo HOA Fees Are Often Higher
If you compare different properties, you will often notice that condo HOA fees are higher than those in detached-home communities. That is not random. Condos typically have more shared physical infrastructure and more shared risk.
A condo association may be responsible for:
- The building exterior
- Roof systems
- Elevators
- Hallways and lobbies
- Fire safety systems
- Parking structures
- Building-wide insurance
- Shared utilities and maintenance staff
By contrast, an HOA in a single-family subdivision may only manage a front entrance, a retention pond, a neighborhood park, or a small pool. Fewer responsibilities usually mean lower fees. So when comparing HOA costs, make sure you are comparing apples to applesnot apples to luxury high-rise elevators with a concierge and a rooftop deck.
What Is a Special Assessment?
A special assessment is an extra charge homeowners may have to pay when regular HOA dues and reserves are not enough to cover a major cost. This can happen after storm damage, urgent repairs, insurance increases, deferred maintenance, lawsuits, or big capital projects.
Examples include:
- A new roof after severe damage
- Concrete or structural repairs
- Major plumbing replacement
- Unexpected legal costs
- Large insurance shortfalls
- Emergency repairs to shared systems
Special assessments are one of the biggest reasons buyers should review an HOA’s finances before closing. A low monthly fee can look attractive right up until you learn the association is underfunded and planning a $7,000 one-time charge. Suddenly, that “affordable” condo starts acting like it has a secret subscription service.
How to Tell If an HOA Fee Is Reasonable
Do not judge an HOA fee by the number alone. Judge it by the value, coverage, and financial condition behind it.
Look at What Is Included
If the fee covers water, trash, exterior maintenance, shared insurance, landscaping, and amenities, a higher number may make perfect sense. If it covers almost nothing but still feels steep, that deserves a second look.
Review the Reserve Fund
A strong reserve fund suggests the board is saving for the future. A weak one can mean future dues increases or special assessments. Buyers should ask whether the community has a reserve study and whether major projects are already expected.
Read the Budget and Financial Statements
Look for signs of stress: rising delinquencies, repeated budget shortfalls, deferred maintenance, or heavy dependence on special assessments. An HOA budget can tell you a lot about whether the community is being run like a businessor like a middle school fundraiser that somehow got access to a roofing contract.
Ask About Upcoming Repairs
A roof, elevator overhaul, façade work, repaving project, or major insurance renewal can all affect future costs. The monthly fee today is only part of the story. The next 12 to 36 months matter too.
Compare Similar Communities
Compare fees among properties of similar age, location, size, and amenities. A townhouse development with no pool is not a fair comparison for a condo tower with a gym, doorman, garage, and master policy.
Red Flags Buyers Should Watch For
Before buying into an HOA, watch for these warning signs:
- Fees that seem unusually low for the level of maintenance required
- Recent or frequent special assessments
- Poorly maintained common areas
- Little or no reserve savings
- Sharp fee increases with no clear explanation
- Ongoing lawsuits or insurance problems
- A large number of owners behind on dues
None of these automatically means “run.” But they do mean “slow down, read everything, and ask better questions.” In real estate, surprises are rarely the fun kind.
Common Experiences Homeowners and Buyers Run Into
One of the most common experiences buyers describe is the moment they realize the HOA fee changes the monthly payment more than expected. A property may look affordable on paper, but once the fee is added, the gap between “doable” and “stretching it” gets very small. This is especially true with condos, where the fee can be large enough to function like a second mini-payment every month.
Another common experience is discovering that a higher HOA fee is not always bad news. Some homeowners initially panic when they see a bigger number, only to find out that the fee includes water, trash, exterior maintenance, landscaping, shared insurance, and a healthy reserve contribution. In that case, the monthly payment may actually be more predictable than owning a detached home where every repair arrives solo and uninvited.
Then there is the opposite experience: the suspiciously low fee. Buyers often love it at first. It feels like they have found the magical unicorn of community living. But after a little digging, they sometimes discover that the association has not built adequate reserves, has delayed maintenance, or has major repairs coming soon. That low fee can be less of a bargain and more of a teaser trailer for future pain.
Homeowners also talk about how HOA value depends on lifestyle. Someone who regularly uses the pool, gym, dog park, walking trails, and clubhouse may feel the fee is money well spent. Another owner who never touches those amenities may feel like they are financing a very exclusive resort they forgot to visit. That does not mean the fee is unfair; it means buyers should be honest about how they live before deciding whether the community fits.
Many condo owners describe a learning curve around insurance. At first, they assume the HOA’s master policy covers everything. Later, they realize it usually covers common structures and shared areas, while they still need their own condo policy for interior elements, personal property, and liability. That misunderstanding can get expensive if it is discovered after damage instead of before move-in.
Another frequent experience involves special assessments. Even when owners understand the concept, they are still caught off guard by the size or timing. A building may need a new roof, structural repairs, or major plumbing work, and the reserve fund may not be enough. Suddenly, every owner is handed a bill that was nowhere in their monthly budget. It is not unusual for buyers to say that nobody clearly explained this risk before closingeven though it is one of the most important things to understand.
And finally, many residents say the real difference is not just the amount of the HOA fee, but how transparently the board communicates. Owners are far more comfortable paying dues when they can see clean financials, a logical budget, planned maintenance, and evidence that the money is being used responsibly. In other words, most people can handle paying for value. What they hate is paying for mystery.
The Bottom Line
So, what are HOA feesand what do they actually pay for? In most communities, they pay for the shared pieces of homeownership that no one person can manage alone: maintenance, amenities, insurance, administration, repairs, and reserve savings for future work. They exist to keep common property functioning, looking decent, and avoiding the financial version of duct tape as a long-term plan.
That said, HOA fees are not just a number to shrug at during the buying process. They are part of your monthly housing cost, part of your risk profile, and part of your day-to-day ownership experience. A reasonable fee with strong reserves and clear coverage can be a sign of a healthy community. A low fee with weak finances can be a trap dressed as a bargain.
The smartest move is simple: ask what the fee covers, what it does not cover, how strong the reserves are, whether any special assessments are coming, and whether the community’s financial records actually support the asking price. Because when it comes to HOA living, the fee itself is only half the story. The other half is whether that money is doing real workor just quietly warming up for your next surprise bill.